Correcting a previously filed payroll tax return with Form 941-X
Why payroll return errors call for a formal correction
An error on a filed Form 941 can come to light weeks or months later. To fix it, the IRS uses Form 941-X, the Adjusted Employer’s Quarterly Federal Tax Return or Claim for Refund.
How the form applies generally depends on the quarter, the type of error, and the current IRS instructions.
What Form 941-X can correct
Under the IRS approach to correcting employment taxes, Form 941-X is the correction form for Form 941. According to the instructions, it may correct the following items.
- Wages and tips
- Federal income tax withheld
- Taxable Social Security wages and tips
- Taxable Medicare wages and tips
- Additional Medicare Tax wages
- Certain credits
When Form 941-X fits and when it may not
Form 941-X is meant for a quarter in which a Form 941 was already filed. If no Form 941 was filed for that quarter, the instructions point to filing the original Form 941 instead.
The instructions also call for a separate Form 941-X for each quarter being corrected. As a result, errors in two quarters would generally mean two forms.
Matching the process to the type of error
The right process depends largely on whether tax was underreported or overreported. When too little tax was reported, the instructions point to the adjustment process, and the extra amount owed is paid at filing.
When too much was reported, employers may choose either the adjustment or the claim process. That choice is still subject to the instructions and the time limits that apply.
IRS Publication 15 adds that both kinds of corrections for the same period generally go on one Form 941-X. A refund request changes this, because Publication 15 then calls for two forms, one for the underreported amounts and one for the refund claim.
The instructions also note a limit on claims. A refund claim is not the route for correcting federal income tax or Additional Medicare Tax actually withheld from employees.
General time limits for corrections
The Instructions for Form 941-X set general time limits.
- Overreported tax. Corrections can generally be made within three years after Form 941 was filed or two years after the tax was paid, whichever is later.
- Underreported tax. Corrections can generally be made within three years after Form 941 was filed.
- Early filing. A Form 941 filed before April 15 of the next year is treated as filed on that April 15 for this calculation.
Federal income tax withholding generally follows a narrower rule. Corrections typically apply to errors found in the same calendar year the wages were paid, while prior-year corrections are generally limited to administrative errors.
How the five parts of the form fit together
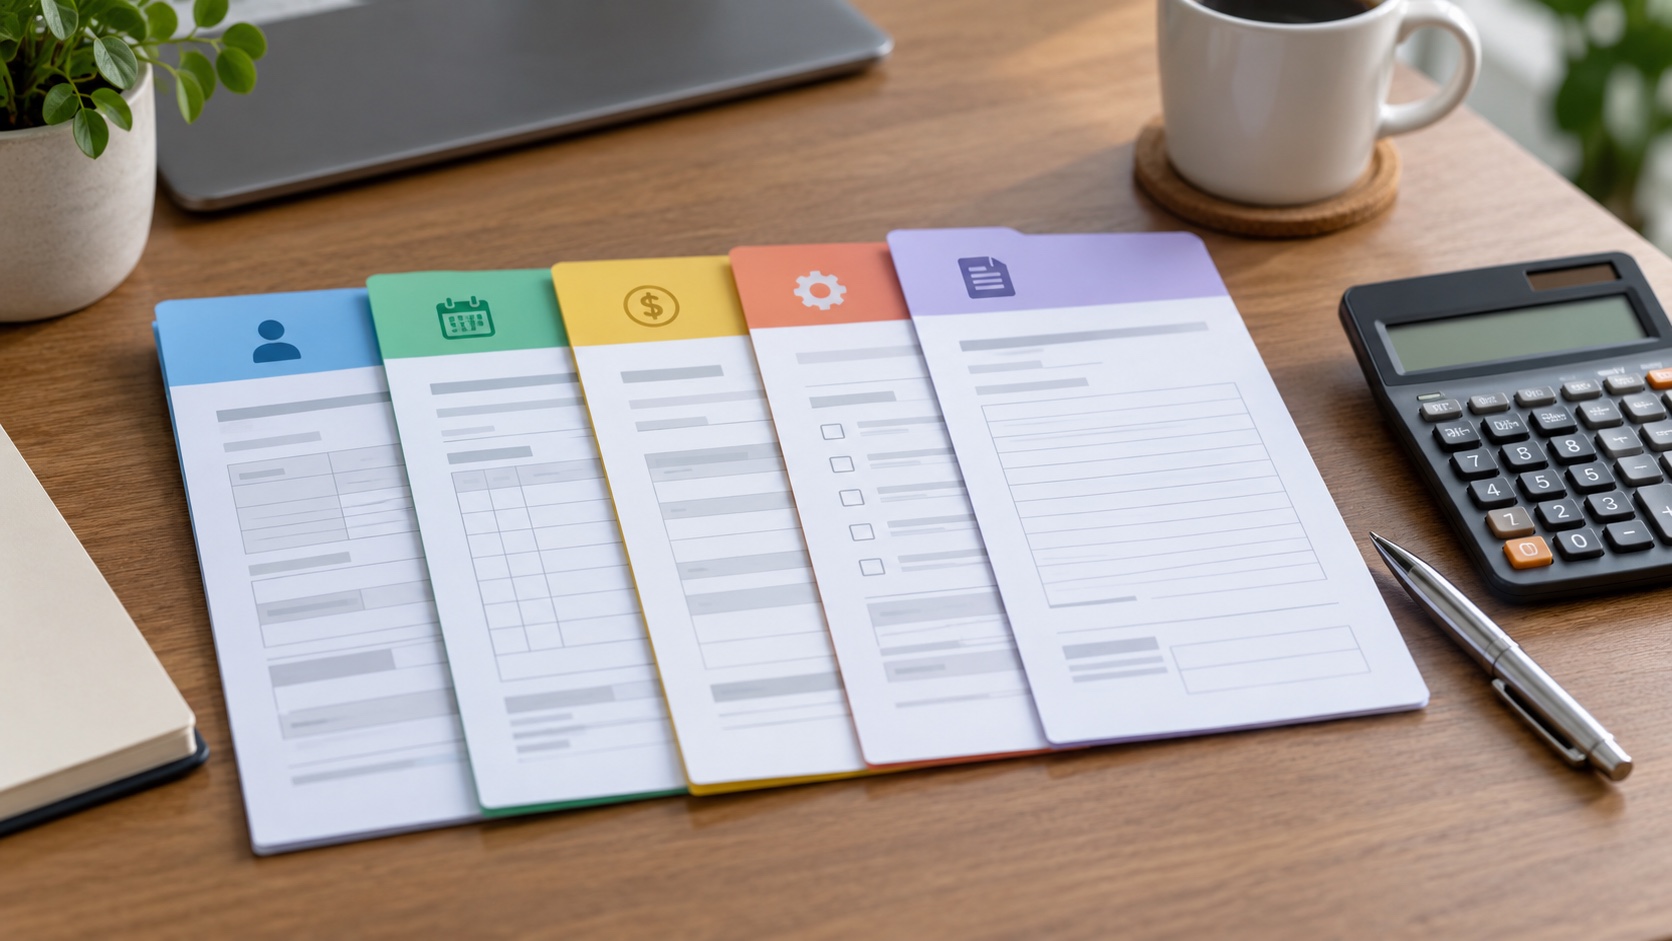
Each part of Form 941-X plays its own role in the correction.
- Part 1 selects the adjustment or claim process.
- Part 2 holds the required certifications.
- Part 3 shows the corrected amount, the amount reported before, and the difference. It also shows the tax correction that results.
- Part 4 explains in detail what happened and why for each correction. The instructions caution that a generic explanation may not be enough and could slow processing.
- Part 5 is for an authorized signature.
Employee wage statements, repayment, and consent
Part 2 includes certifications about Forms W-2 and W-2c. Because of that, a correction may also involve the wage statements employees received.
For some overreported employee taxes, the certifications may also involve employee repayment, reimbursement, or consent.
Preparing payroll records for a correction
Publication 15 notes that employers should keep records that support their returns and corrections. It also calls for reconciling payroll records with Forms W-2 and W-3.
With that in mind, these items are useful to gather first.
- The originally filed Form 941 for the quarter
- Payroll records that support the corrected figures
- Corrected amounts, previously reported amounts, and differences for each affected line
- Notes on what caused each error, to support Part 4
- Any Forms W-2c and records of employee repayments, reimbursements, or consents
- The original filing date and the dates tax was paid
Avoidable mistakes to watch for
- Filing Form 941-X with no original Form 941
- Combining quarters on one form
- Selecting both Part 1 processes
- Requesting a refund alongside underreported corrections
- Writing a vague Part 4 explanation
- Using outdated forms or instructions
Keeping a Form 941-X correction accurate and well supported
Before filing, reviewing the current IRS Instructions for Form 941-X helps keep a correction in line with the latest guidance.
Corrections that span several quarters, involve credits, or need employee consent can take extra care. In those cases, a qualified payroll or tax professional may help confirm the approach.
This article provides general information and is not tax advice.
Frequently Asked Questions About Form 941-X
Does Form 941-X also correct Form 941-SS?
Yes. According to the instructions, Form 941-X is also used to correct a previously filed Form 941-SS.
What counts as an administrative error for prior-year withholding?
The instructions describe it as a mismatch between the amount reported and the amount actually withheld. A transposition or math error is one example.
Where can the current form and instructions be found?
The IRS About Form 941-X page provides the current form and instructions. It also offers prior revisions, payment information, and employment tax e-file resources.
Is Form 941-X filed together with the regular quarterly Form 941?
Generally, no. The instructions indicate that Form 941-X is generally filed separately from Form 941.
Can Form 941-X be filed electronically?
Yes. The IRS encourages employers to file Form 941-X electronically through Modernized e-File.